 S3 Enterprise
14 screens
Assets
What the company owns for its own use - buildings, machines, computers, vehicles: what each cost, where it is, who has it, and how much it has depreciated. Every page in the Assets menu, what it is for, and where it leads; then the asset itself, tab by tab. The pictures are the demo company (Foundry Valves) after the test runs, so the names and numbers are made up.
An asset's life
An asset is not stock: it is not sold, it is used, and its cost is spread over its life as depreciation.
The work
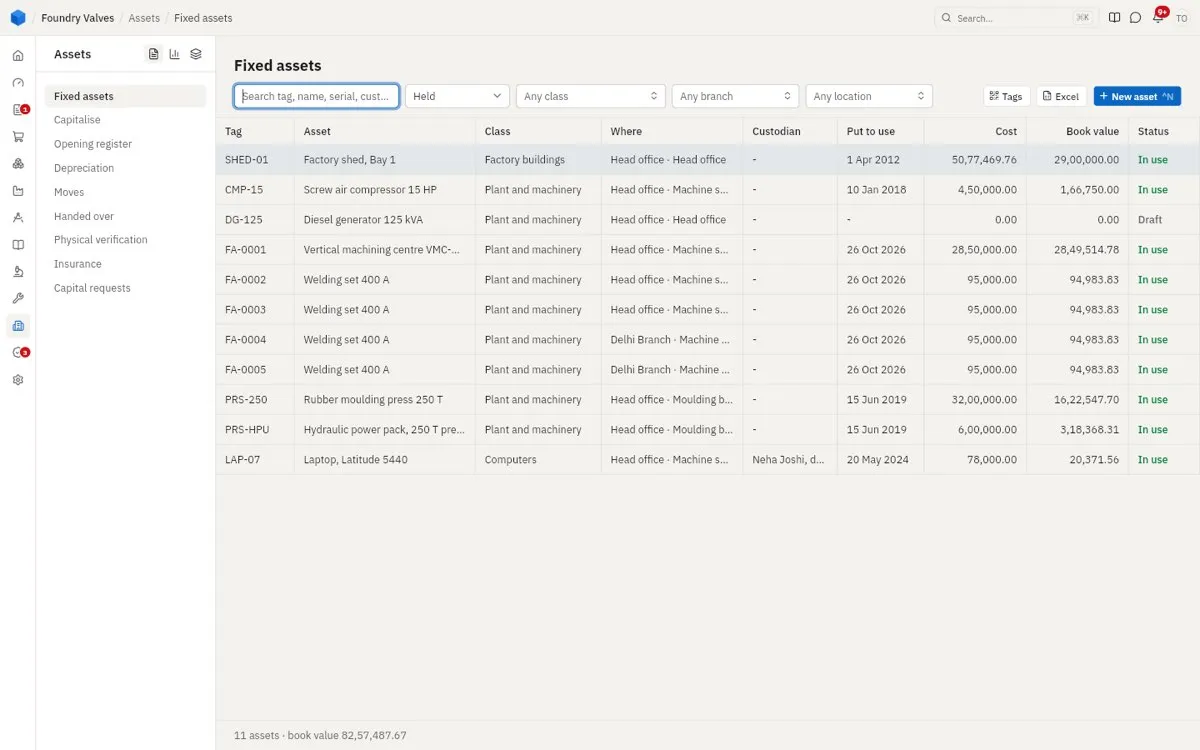
Fixed assets
The register: every asset's tag, class, where it is, its custodian, when it was put to use, its cost and book value, and status (draft, in use, sold, scrapped). Tags prints their labels.
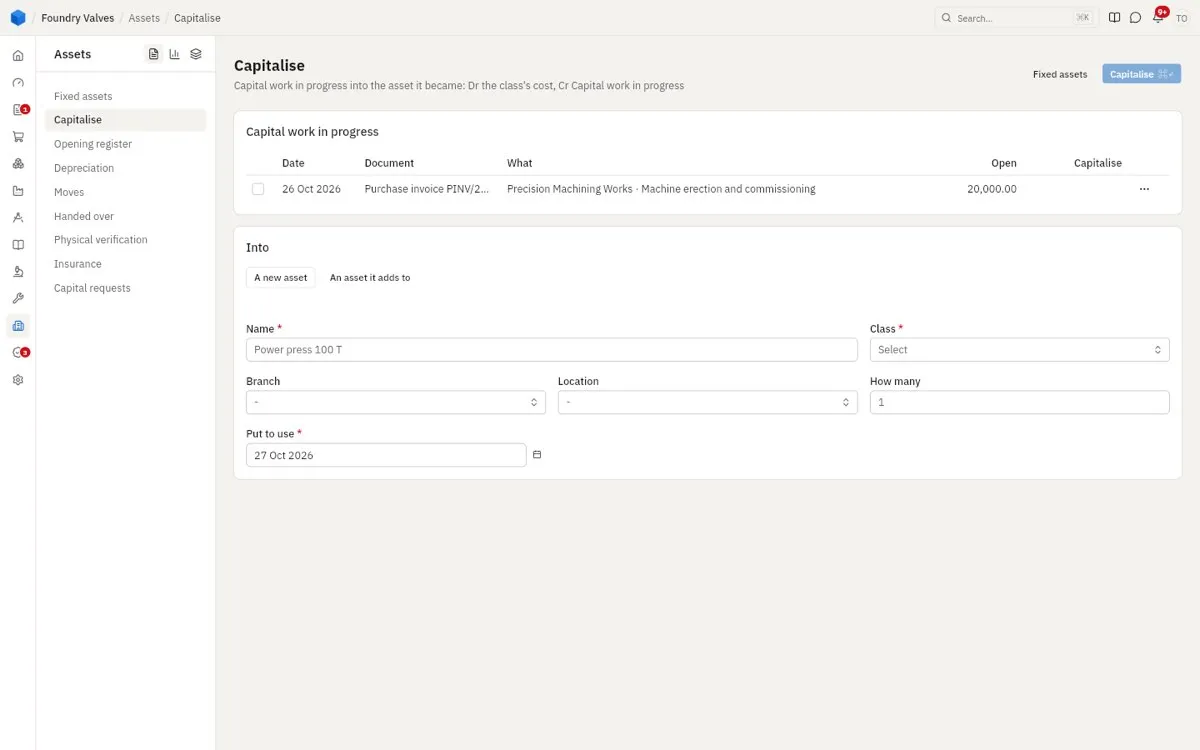
Capitalise
Capital work in progress - bills for a machine still being put up, erection and commissioning - turned into the asset it became, or added to one that exists.
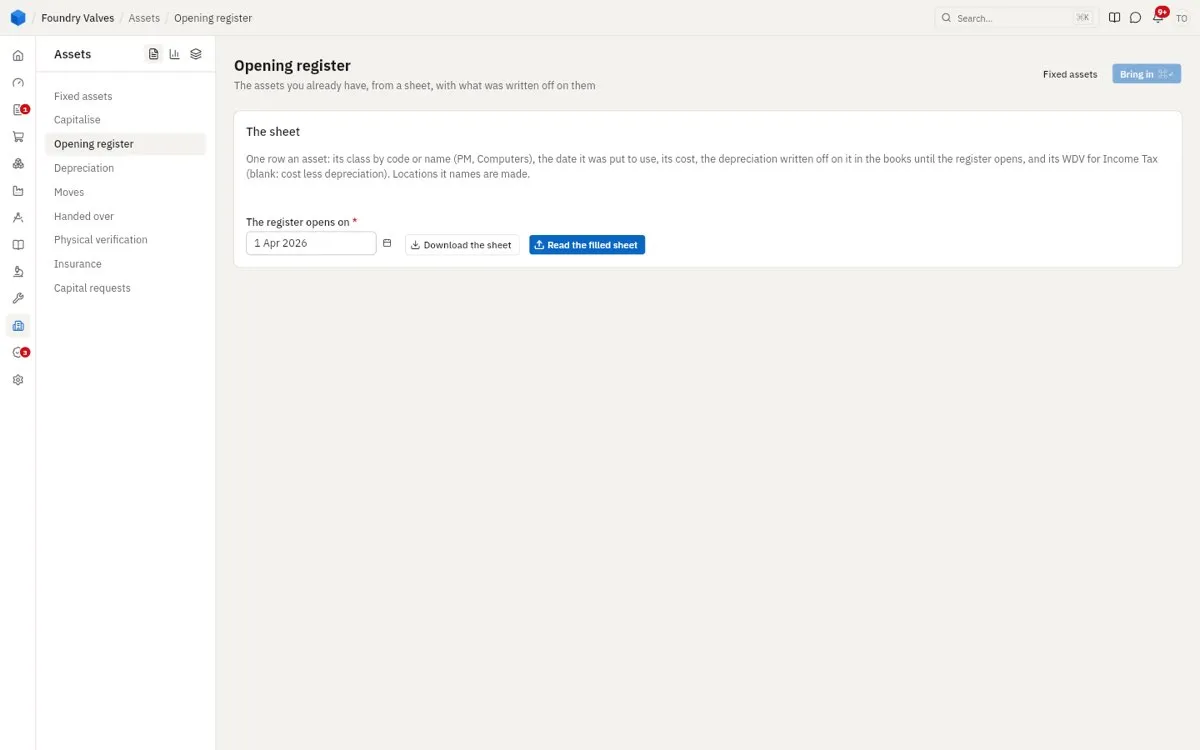
Opening register
The assets the company already has, brought in from a sheet: each one's class, date put to use, cost, the depreciation written off so far, and its tax written-down value.
Depreciation
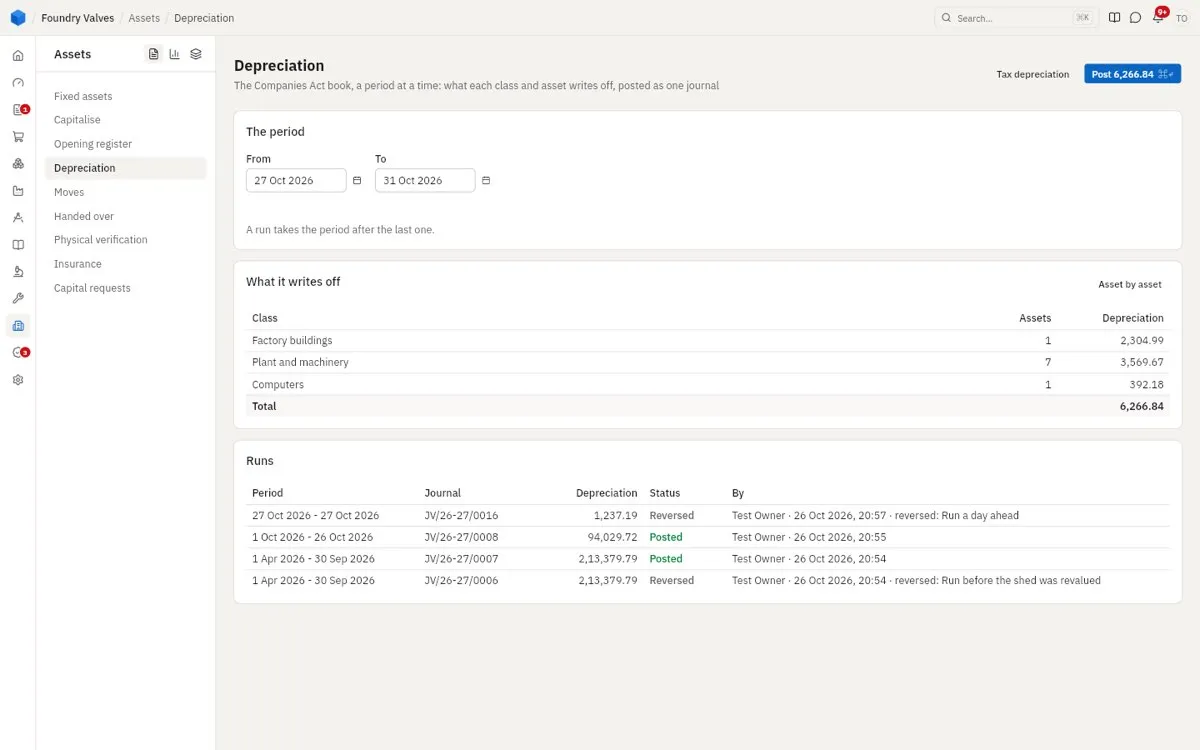
The Companies Act book, a period at a time: what each class writes off, posted as one journal. A run can be reversed, with why.
Moves
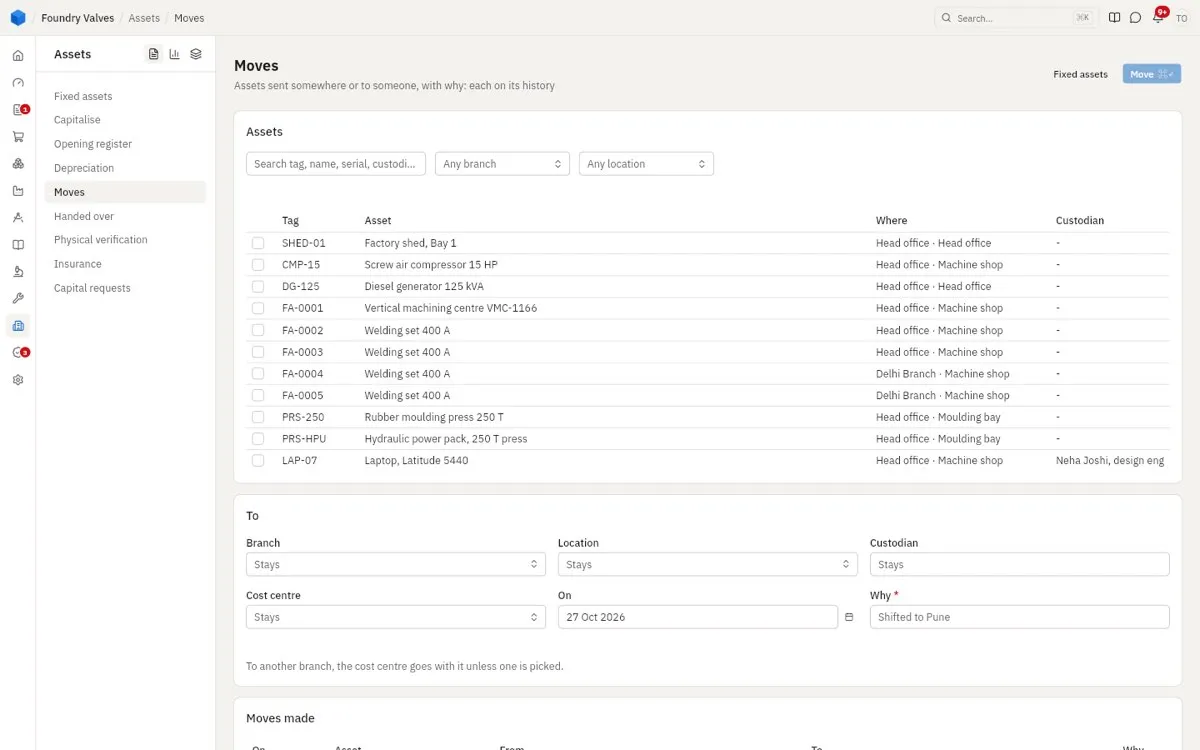
Assets sent to another plant, place or person, with why - each one on the asset's history.
Handed over
Assets handed to a person (a laptop to an engineer), until they are taken back.
Physical verification
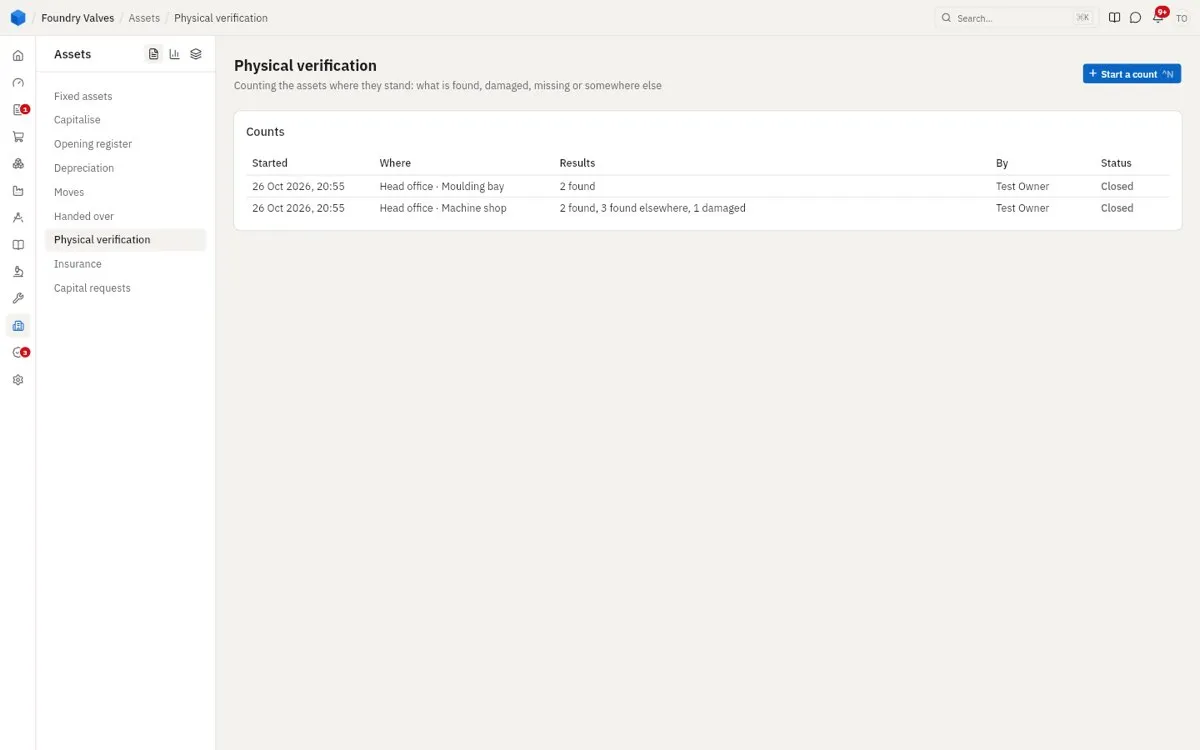
Counting assets where they stand: what is found, damaged, missing or somewhere else. The auditors ask for it.
Insurance
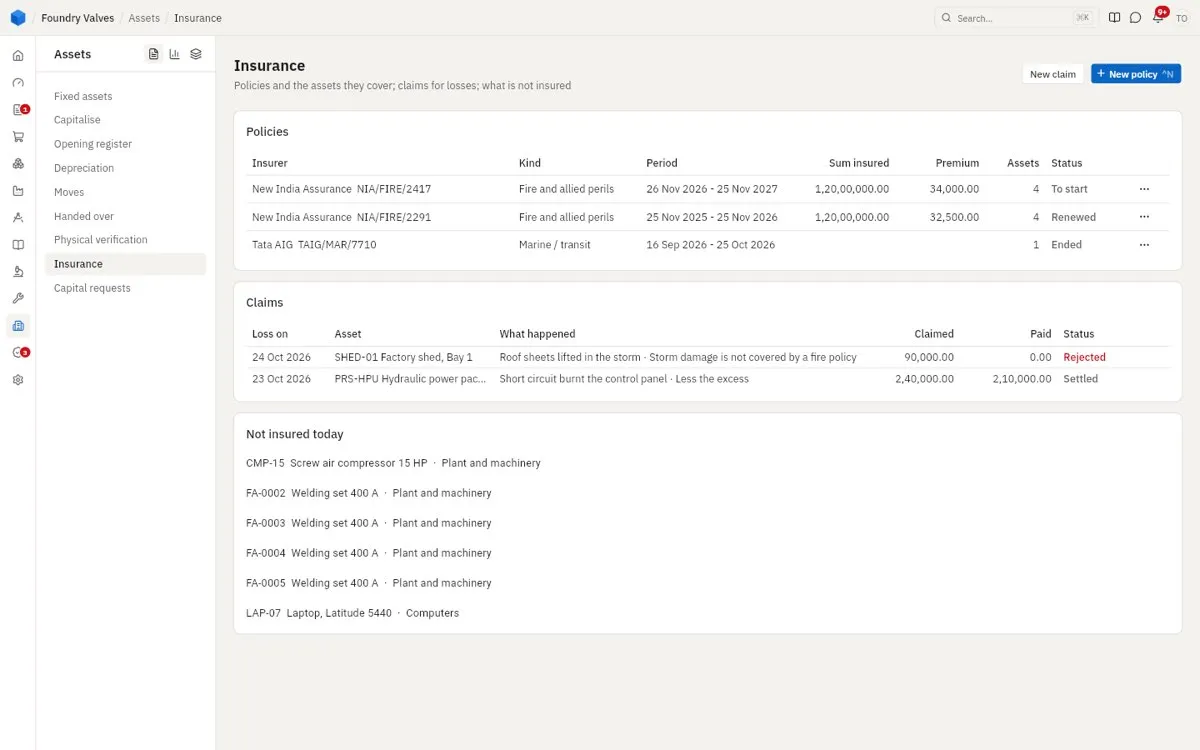
Policies and the assets they cover, claims for losses and what was paid, and what is not insured today.
Capital requests
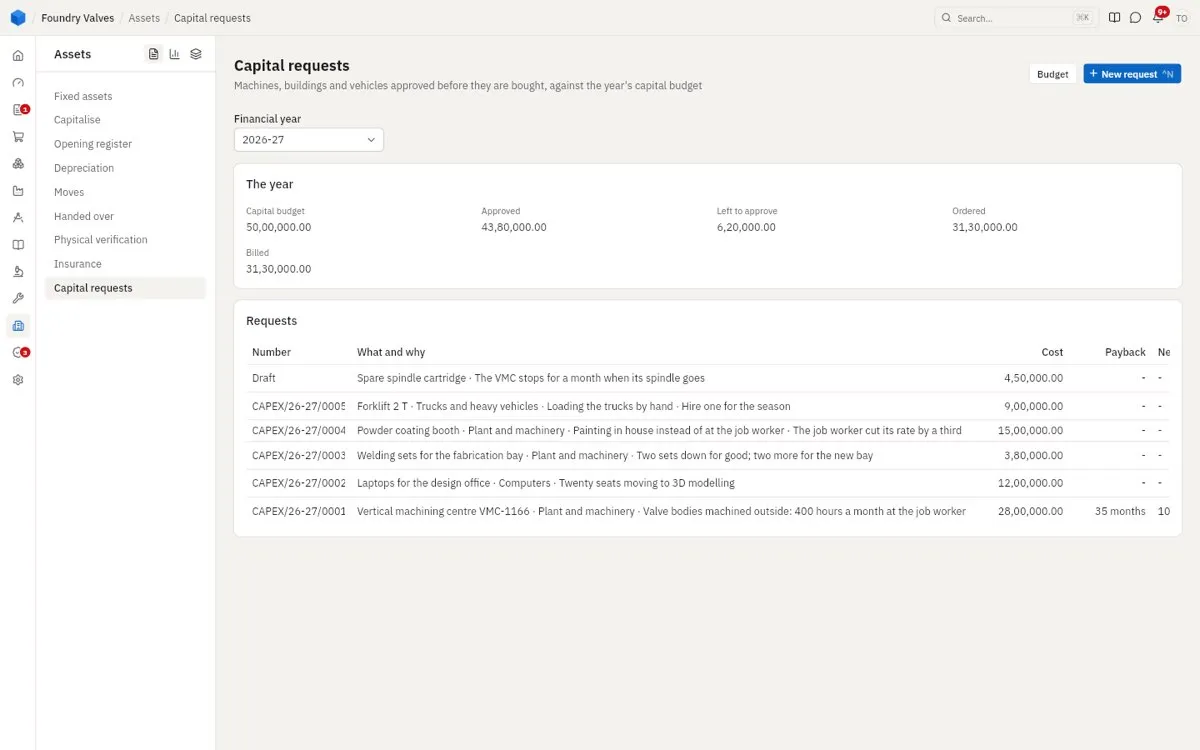
Machines, buildings and vehicles asked for and approved before they are bought, against the year's capital budget: what and why, the cost, its payback. The year's budget, approved, ordered and billed at the top.
Masters
Asset classes
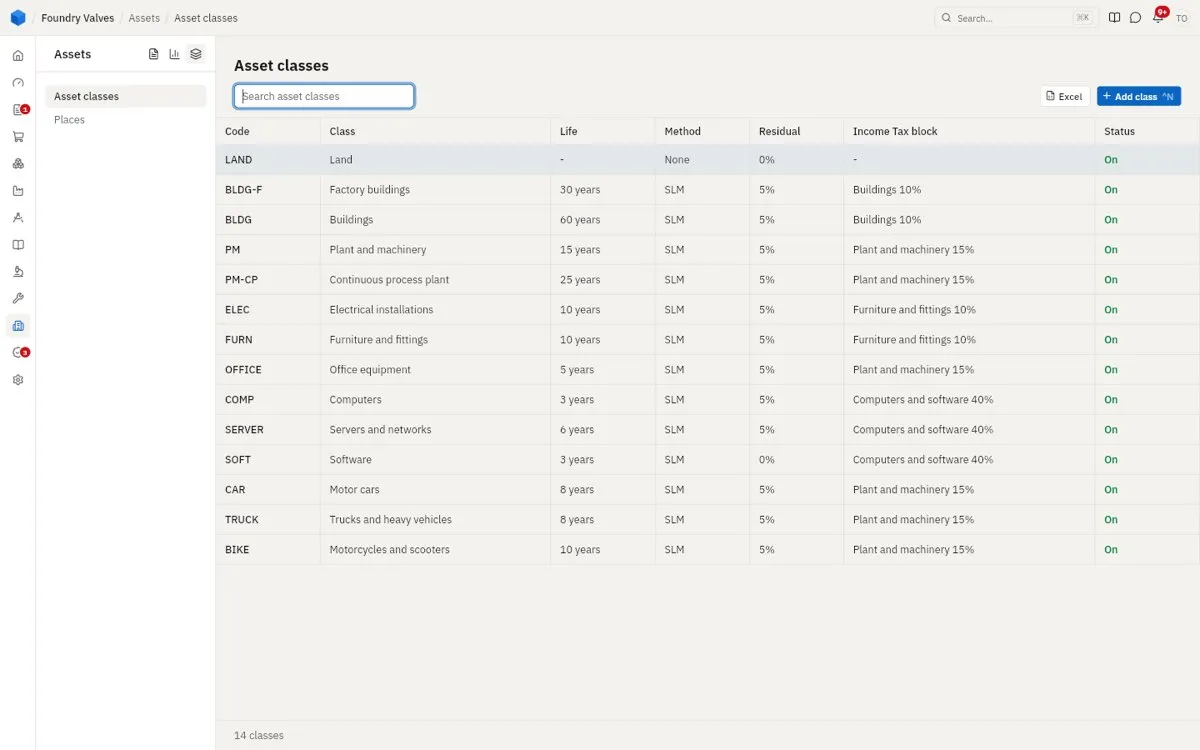
Kinds of asset (factory buildings, plant and machinery, computers, motor cars): each one's life, depreciation method, residual value, and its Income Tax block.
Places
Where assets stand - a plant, a shop inside it.
Reports
Asset reports
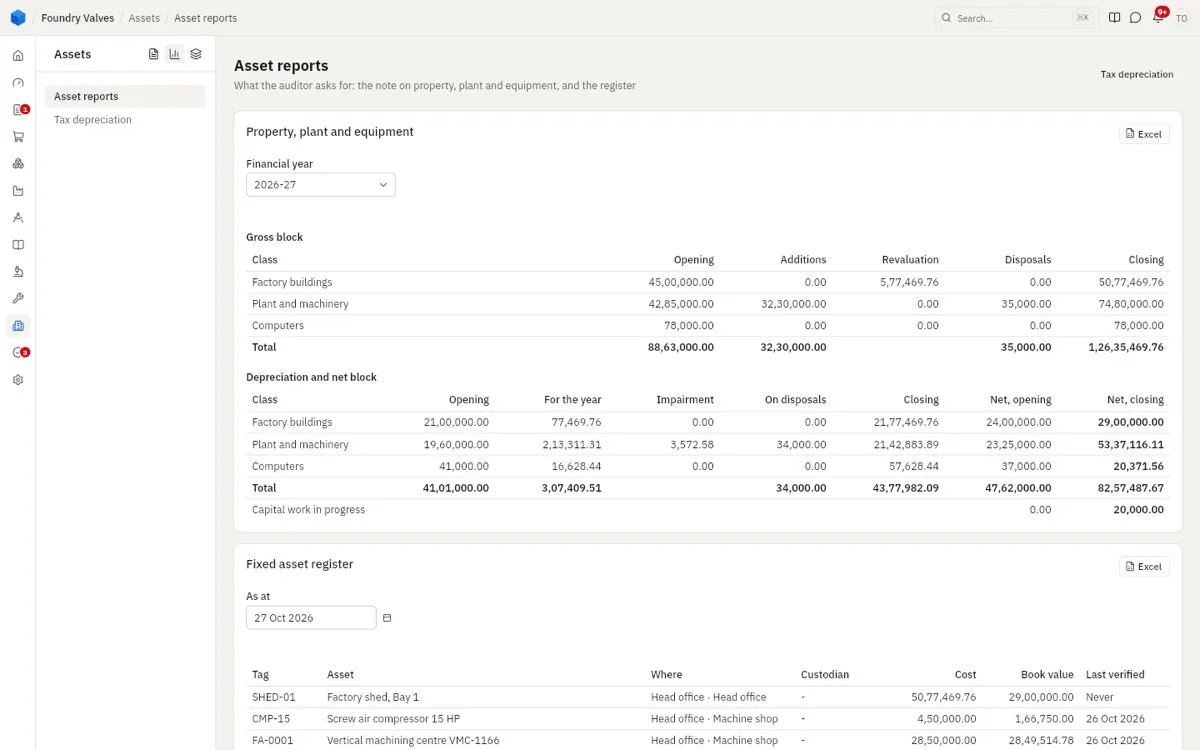
What the auditor asks for: the note on property, plant and equipment - gross block, depreciation and net block by class (opening, additions, revaluation, disposals, closing) - and the fixed asset register as at a date.
Tax depreciation
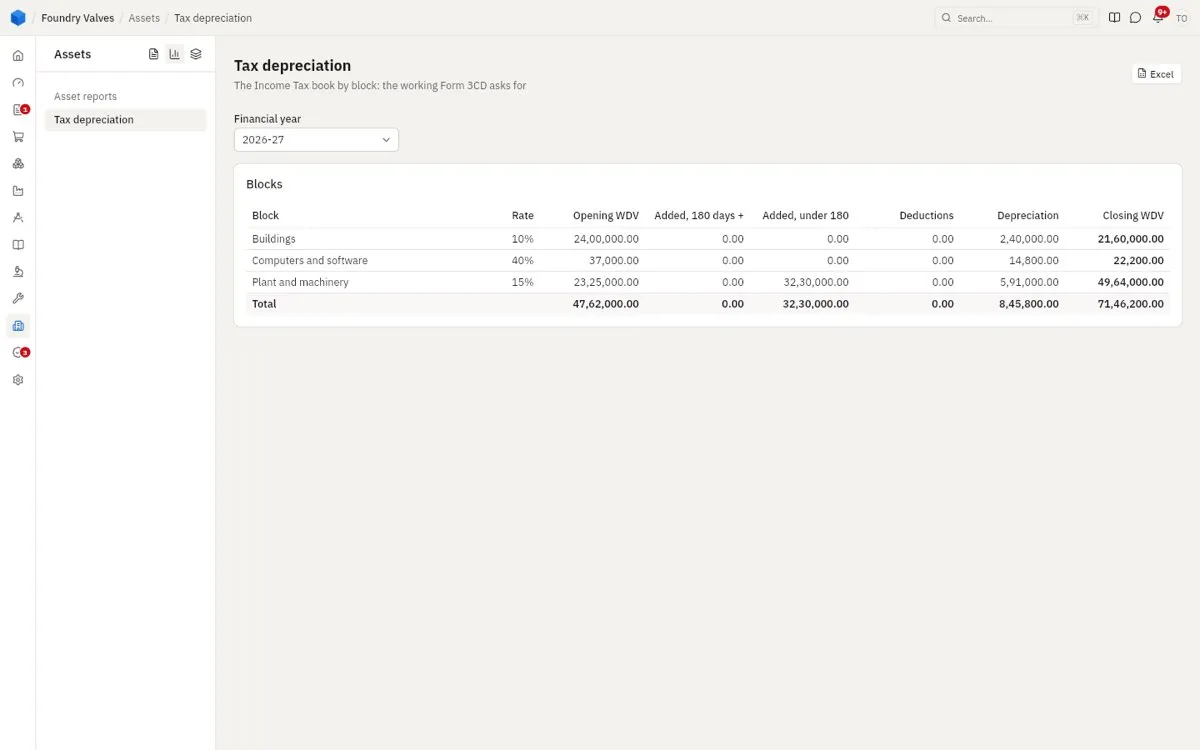
The Income Tax book by block: opening WDV, additions (over and under 180 days), deductions, depreciation and closing WDV - the working Form 3CD asks for.
The asset, tab by tab
Fixed asset
Tag, name, class, and what it is part of up top. At its foot: Tag (print its label), Its invoice, Save. Tabs:
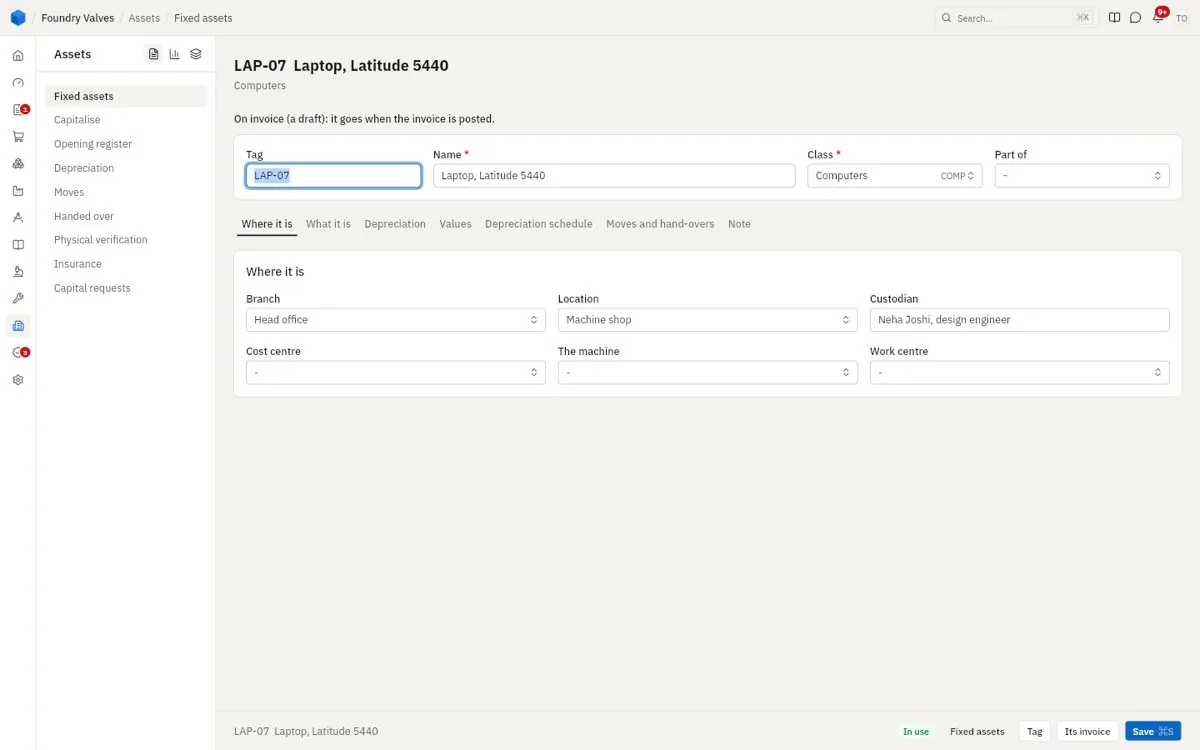
- Where it is: plant, place, custodian, cost centre, the machine and work centre it is
- What it is: maker, model, serial, supplier, warranty, GST credit taken
- Depreciation: put to use, life, method, residual %, extra shifts
- Values: cost, depreciation and book value in each book, and every entry
- Depreciation schedule: what is posted and still to come, year by year
- Moves and hand-overs: where it went, to whom, why
- Note